The Contract Poultry & Hog Growers Fix Kit
Built for contract poultry and broiler growers and contract hog farmers.
You own the houses and carry the debt. This kit finds where the money leaks in your own work and gives you the steps and the words to close each one.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
The 7 leaks it covers
1 you can close it · 3 the other side owes it · 3 a pro decides
- Swings in settlement income meeting fixed house debt (framing row)Where to look first: The risk here is the swing, not a low average. List your fixed yearly costs: house loan payments, insurance, utilities you pay even between flocks.Keep it from coming back: Judge every new loan against your worst settlement year, not your average.You can close it
- Never used the company's settlement-history disclosureWhere to look first: Ask the company for its current disclosure document if you don't have one. Under the 2023 USDA rule it must be given to you at least 14 days before you sign a renewal or new contract.Keep it from coming back: Never sign a renewal without the disclosure document in hand at least 14 days before.The other side owes it
- Mortality and condemnation charges that may trace to company inputsWhere to look first: Keep your own daily mortality log with causes you can see, and first-week deaths separately.Keep it from coming back: Log mortality daily and ask for condemnation detail with every settlement.The other side owes it
- Tournament ranking moved by inputs the company controlsWhere to look first: For every flock, keep your own sheet: placement date, chick count, breed and breeder-flock age (from the placement paper), feed deliveries and any feed problems, daily mortality, catch date.Keep it from coming back: Start a flock sheet on placement day, every flock. Ask for any missing disclosure the same week.The other side owes it
- Counting on a base-pay floor rule that is not in forceWhere to look first: Judge your settlement only against what your own contract says about base pay and deductions — not against the 2025 USDA payment-systems rule.Keep it from coming back: Put any pay floor you're counting on into the contract itself.A pro decides
- Self-employment tax on settlement income (boundary, not owed by the company)Where to look first: Not money the company owes you. It's a cost on your farm profit you should plan for. Each settlement, write down the date and amount.Keep it from coming back: Set aside on every settlement, not at tax time.A pro decides
- Company-required house upgrade financed by you with no pay change promisedWhere to look first: Before agreeing to any required upgrade, ask the company in writing: what exactly is required, by when, what happens if you don't, and whether your pay rate, number of flocks, or contract length changes after.Keep it from coming back: Get pay, placements and term in writing before taking on any upgrade debt.A pro decides
Free: one full leak from this kit
No sign-up, no email. Here is leak 1 of 7 exactly as it appears in the kit, so you can see what you get before you buy.
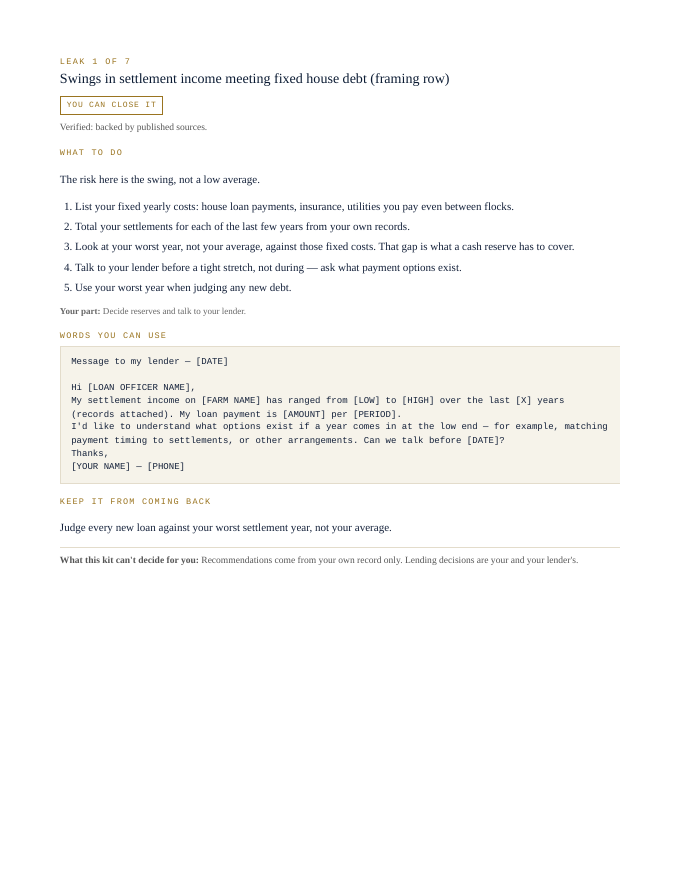
Swings in settlement income meeting fixed house debt (framing row)
You can close itThe risk here is the swing, not a low average.
- List your fixed yearly costs: house loan payments, insurance, utilities you pay even between flocks.
- Total your settlements for each of the last few years from your own records.
- Look at your worst year, not your average, against those fixed costs. That gap is what a cash reserve has to cover.
- Talk to your lender before a tight stretch, not during — ask what payment options exist.
- Use your worst year when judging any new debt.
Your part: Decide reserves and talk to your lender.
Message to my lender — [DATE]

Hi [LOAN OFFICER NAME],
My settlement income on [FARM NAME] has ranged from [LOW] to [HIGH] over the last [X] years (records attached). My loan payment is [AMOUNT] per [PERIOD].
I'd like to understand what options exist if a year comes in at the low end — for example, matching payment timing to settlements, or other arrangements. Can we talk before [DATE]?
Thanks,
[YOUR NAME] — [PHONE]
Judge every new loan against your worst settlement year, not your average.
What this kit can't decide for you: Recommendations come from your own record only. Lending decisions are your and your lender's.
That's 1 of 7. The other 6 come the same way in the kit: steps, words to send, a habit to keep each one closed.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
What people in this work look up
When contract poultry and hog growers go looking for answers, they search things like “contract poultry farming”, “packers and stockyards act”, “poultry tournament system” and “chicken house income”. Those searches turn up forms, averages and other people's numbers. This kit starts from your own records instead: the 7 places money leaks in this work, where to look first and the words to send to close each one.
What you get for each leak
- Numbered steps to close each leak
- Your part, spelled out
- Words you can use: letters and scripts, ready to send (fill in the brackets)
- A habit that keeps each leak from coming back
- An honest line on what the kit can't decide for you
A page from the kit
Questions people ask
How does the poultry tournament system affect my pay?
Your ranking can move with inputs the company controls, like birds and feed. The kit shows what to record so you can see it in your own settlements.
Can I see my company's settlement history?
Integrators must give you a settlement-history disclosure, and most growers never use it. The kit shows how to ask.
Who pays for a company-required house upgrade?
Often you do, with no pay change promised. The kit lists what to get in writing before you sign.
What it can't decide for you
This kit works from your own records. It doesn't give legal, tax, licensing or financial advice, and it never tells you what to charge. Where a CPA, attorney, insurer or state board makes the call, the kit says so and gets your records ready for them.
11-page PDF · instant download after payment · Code VYR-KIT-BARNES-01
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
Use Jobber or Housecall Pro? Run the free leak check — it reads your job export in your browser and shows the money leaks the software doesn't flag. Nothing is uploaded.