The Loan Officers & Mortgage Brokers Fix Kit
Built for loan officers and mortgage brokers.
In mortgage work, pay is set by rules most people never read: how loan officer compensation may be set, who pays tolerance cures, the hours of education a license needs, and what a broker agreement says happens when a loan pays off early. The leaks hide in those rules and in lead spend nobody traced to a funded loan. Your pipeline, comp plan and agreements are the proof. This kit finds where the money leaks in your own work and gives you the steps and the words to close each one.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
The 8 leaks it covers
4 you can close it · 1 the other side owes it · 3 a pro decides
- Comp plan tied to loan termsWhere to look first: Read your compensation plan line by line.Keep it from coming back: Review your comp plan every time it changes.A pro decides
- Tolerance cures charged back to youWhere to look first: List loans this year where a cure was paid.Keep it from coming back: Recheck fees before every disclosure.You can close it
- License education done late or repeatedWhere to look first: Check your NMLS record for your CE status.Keep it from coming back: Finish CE by midyear.You can close it
- Lead spend never traced to funded loansWhere to look first: List every lead source and what it cost last quarter.Keep it from coming back: Tag every lead with its source.You can close it
- Fallout from slow document collectionWhere to look first: List loans that fell out last quarter and why.Keep it from coming back: Send the full list on day one.You can close it
- Hourly or salaried loan officers working unpaid overtimeWhere to look first: Log your hours for a month, including evenings and weekends.Keep it from coming back: Log hours weekly.The other side owes it
- Broker agreements with early payoff or default clawbacksWhere to look first: Pull every wholesale lender agreement you've signed.Keep it from coming back: Keep a list of loans inside clawback windows.A pro decides
- 1099 or branch income with no tax set asideWhere to look first: If you're paid on a 1099, list every payment this year.Keep it from coming back: Move a set share of each payment the day it lands.A pro decides
Free: one full leak from this kit
No sign-up, no email. Here is leak 1 of 8 exactly as it appears in the kit, so you can see what you get before you buy.
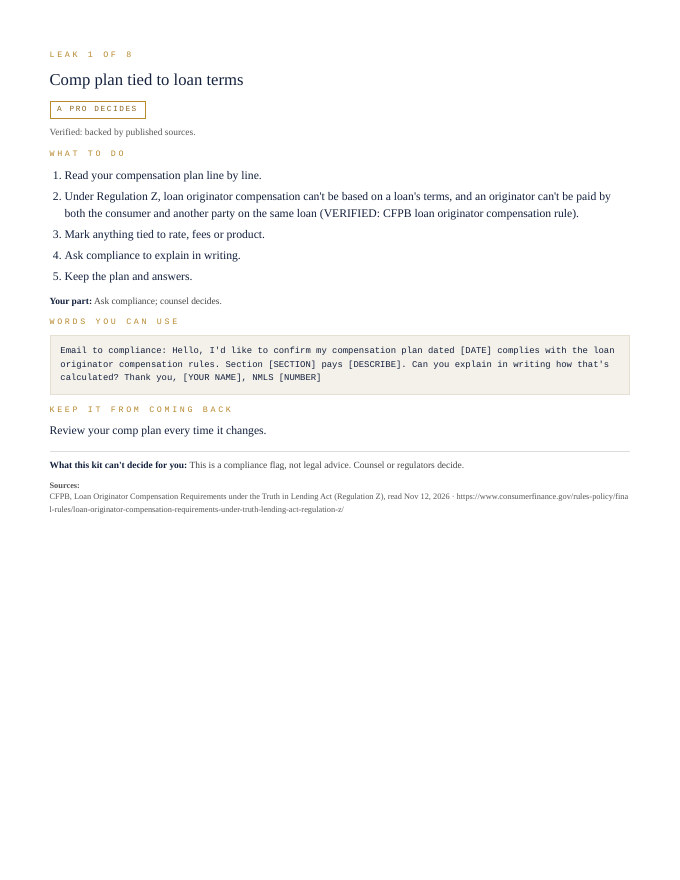
Comp plan tied to loan terms
A pro decides- Read your compensation plan line by line.
- Under Regulation Z, loan originator compensation can't be based on a loan's terms, and an originator can't be paid by both the consumer and another party on the same loan (VERIFIED: CFPB loan originator compensation rule).
- Mark anything tied to rate, fees or product.
- Ask compliance to explain in writing.
- Keep the plan and answers.
Your part: Ask compliance; counsel decides.
Email to compliance:

Hello, I'd like to confirm my compensation plan dated [DATE] complies with the loan originator compensation rules. Section [SECTION] pays [DESCRIBE]. Can you explain in writing how that's calculated? Thank you, [YOUR NAME], NMLS [NUMBER]
Review your comp plan every time it changes.
What this kit can't decide for you: This is a compliance flag, not legal advice. Counsel or regulators decide.
That's 1 of 8. The other 7 come the same way in the kit: steps, words to send, a habit to keep each one closed.
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
What people in this work look up
When loan officers and mortgage brokers go looking for answers, they search things like “loan officer commission”, “loan officer salary”, “mortgage broker fees” and “loan officer compensation”. Those searches turn up forms, averages and other people's numbers. This kit starts from your own records instead: the 8 places money leaks in this work, where to look first and the words to send to close each one.
What you get for each leak
- Numbered steps to close each leak
- Your part, spelled out
- Words you can use: letters and scripts, ready to send (fill in the brackets)
- A habit that keeps each leak from coming back
- An honest line on what the kit can't decide for you
A page from the kit
Questions people ask
Comp plan tied to loan terms: where do I start?
Start here: Read your compensation plan line by line. To keep it from coming back: Review your comp plan every time it changes.
Tolerance cures charged back to you: where do I start?
Start here: List loans this year where a cure was paid. To keep it from coming back: Recheck fees before every disclosure.
License education done late or repeated: where do I start?
Start here: Check your NMLS record for your CE status. To keep it from coming back: Finish CE by midyear.
What it can't decide for you
This kit works from your own records. It doesn't give legal, tax, licensing or financial advice, and it never tells you what to charge. Where a CPA, attorney, insurer or state board makes the call, the kit says so and gets your records ready for them.
14-page PDF · instant download after payment · Code VYR-KIT-MORTGAGE-01
Opens secure checkout. Instant download after payment. 30 days to ask for a refund — refund policy · terms
Next step
- Run your free LeakReceipts check — it reads your own receipts and records and shows where money is leaking out, line by line.
- TrueNET — the whole-picture money truth: what you actually keep after every cost, across everything you earn and spend.
Use Jobber or Housecall Pro? Run the free leak check — it reads your job export in your browser and shows the money leaks the software doesn't flag. Nothing is uploaded.